
U.S.-Based
Banking Software Development
Banking software development by SoftDoes: secure, compliant digital banking platforms that integrate with your core and scale with you.

Let's build together.
Talk with a senior engineer about your product idea, architecture, and what it would take to build it.
90+
Active Client Partnerships
80+ Person
Product & Engineering Team
100%
Your Code & IP Ownership
U.S.-Led
Delivery & Accountability
We understand the challenges you're facing
Why do our teams still reconcile customer and transaction data across spreadsheets and disconnected systems?
When financial data lives in disconnected silos - core banking on one side, card processors on another, payment gateways, CRM systems, loan origination, and KYC tools each holding their own version of the truth - operations teams spend hours reconciling transaction data by hand. SoftDoes designs a centralized banking data layer that standardizes entities such as customers, accounts, ledgers, transactions, and compliance cases into consistent, well-governed data models. Event-driven pipelines and change data capture (CDC) feed real-time dashboards for operations, finance, and risk teams, replacing batch extracts and manual joins. Full data lineage means you can trace a single payment from channel input through postings, reconciliations, and regulatory reports - exactly what auditors and regulators expect. This removes spreadsheet reconciliations, gives your teams one source of truth, and unlocks advanced data analytics across the organization.
Our processes follow AML, KYC, and central bank rules. How do we map them into software without breaking compliance?
Every banking institution operates under layers of regulation - AML directives, KYC protocols, central bank mandates, internal policies - and those rules are embedded in how staff work day to day. SoftDoes reviews your existing AML/KYC procedures, customer onboarding steps, credit evaluation workflows, and internal policies, then models them as configurable workflows, forms, decision trees, and approval chains. We build support for standards and regulations relevant to your markets: PCI DSS, PSD2 and strong customer authentication, GDPR, EU AML directives, SOX, DORA, and ISO 20022 - notably, 40% of US and UK banks are not ISO 20022 compliant, a gap that custom development can close. Maker-checker (four-eyes) controls, granular roles and permissions, and comprehensive audit logs are standard in every module. This approach means your teams change rules and thresholds in configuration rather than waiting for hard-coded fixes with every policy update, helping you maintain regulatory compliance as requirements evolve.
Can new digital products talk to our decades-old core without risking downtime for customers?
Legacy banking systems limit scalability and innovation, but ripping them out overnight is rarely safe or practical. SoftDoes designs API-first architecture and middleware that wraps legacy core systems - whether Temenos, FIS, Fiserv, Jack Henry, Finastra, Oracle FLEXCUBE, Mambu, or a custom in-house platform - without replacing them outright. Integration adapters, message queues, and the strangler pattern let new services run alongside old ones with parallel posting and real-time reconciliation to the cent. Phased go-lives happen during agreed maintenance windows, with rollback plans and feature flags so banking applications maintain near-zero downtime for customer access. Custom banking software development lets teams launch new digital products and channels while de-risking core banking modernization - one domain at a time.
Why do our banking apps feel like they were built for compliance officers, not for customers and staff?
Banking software must support customer experience and accessibility standards, not just internal controls. SoftDoes runs user research and interviews with customers, branch staff, contact center agents, back office operations, and compliance teams to understand what each group actually needs from the interface. We design role-specific UIs: simple, fast mobile banking apps and online banking platforms for customers, efficient case queues and bulk-action tools for operations, and dashboards with drill-downs for leadership and risk committees. Low-friction digital onboarding with built-in identity verification, clear progress states, and secure but quick authentication - MFA, biometrics, PSD2 SCA - reduces errors, call volume, and training time. Accessible layouts meet WCAG 2.1 AA, so every user can interact with your banking services confidently.
If regulations change or we launch a new product next year, are we stuck in a rigid platform again?
Digital transformation enables banks to launch new products quickly - but only if the underlying platform is designed for change. SoftDoes builds modular architecture with clear domain boundaries: customers, accounts, ledgers, payments, cards, lending, compliance. A configurable product catalog handles fees, interest rates, limits, eligibility rules, and bundles, so product teams update parameters without engineering intervention. Workflow engines, extension points, feature toggles, and versioned APIs - including open banking APIs that help comply with PSD2 regulations - let you evolve features with minimal disruption. We produce thorough technical and process documentation so your internal teams can adjust rules, add partners, and enter new markets without vendor dependence for every change. Microservices architecture allows independent scaling of software modules as transaction volumes and product complexity grow.
You run the bank. We engineer the software behind it.

Custom Digital and Core Banking Platforms
We design core banking systems and digital banking platforms tailored to your institution's products, customer journeys, and operating model, replacing generic vendor templates with software that fits your reality. Typical modules include digital onboarding and KYC, customer and account management, double-entry ledgers, payments and transfers, card management, loan origination and servicing, and back-office case management.
Configurable product catalog for fees, interest, limits, and eligibility rules - no code changes for routine product updates.
Strong customer authentication and secure session management across web, mobile banking, and internal channels.
Double-entry ledger with a full audit trail for every posting, adjustment, and reversal.

Banking Data Integration and Analytics
SoftDoes connects scattered financial data from core banking, card processors, payment rails (SWIFT, SEPA, ACH, RTP), CRM systems, digital channels, KYC/AML providers, and loan systems into a coherent data ecosystem. Data lakes, event streams, and BI dashboards surface liquidity positions, risk exposures, and customer behavior trends in near real time rather than in yesterday's batch report.
Real-time transaction monitoring and anomaly detection dashboards for operations and risk management teams.
Automated generation of regulatory reporting and management reports from a clean, governed data layer.
Customer 360 views with drill-down for risk committees, executive reviews, and relationship managers.

AI Enhanced Banking Workflows
AI-powered solutions can detect fraudulent activities early, prioritize AML alerts, support credit evaluation, predict churn, and automate intelligent document processing for KYC and loan files. AI adoption can increase banking profitability by 11% or more, but models in banking must work within regulated environments - with explainable outputs, support for model risk management, and alignment with fair lending expectations.
Natural language summaries of AML and fraud investigations for compliance officers.
Predictive credit and churn risk scores integrated directly into lending and CRM flows.
Next-best-action suggestions for contact center agents and relationship managers to improve customer satisfaction.
Numbers Don’t Lie
Recent projects showcasing how we design, engineer, and deliver production-ready software solutions.

- Startup
- Real Estate
Our Haus AI
A finance professional turned founder built Our Haus AI, an AI-powered collaborative workspace where homeowners and contractors scope, bid, contract, and document renovation projects together. SoftDoes took her prototype and made it production-ready.- 10XMVP scope delivered
- 2+years Ongoing partnership
- 1Fully owned Platform

- Finance
- Energy
Deepwater Insights
Deepwater Insights delivers proprietary alternative data and niche research on the offshore drilling and energy sector to institutional investors, family offices, and high-net-worth individuals who require coverage that larger firms don't provide.- 100%Brand Continuity
- 2Platform Distribution
- 100%Paywall-Ready Content

- Real Estate
The building buyer
The Building Buyer is a Florida-based real estate investment firm co-founded by Dylan Troiano and Charles Hanlin. They acquire single-family, multifamily, and commercial properties across South Florida and beyond, with a focus on motivated seller opportunities.- 18Weekly hours saved
- 2+Years Ongoing partnership
- 1Fully owned Platform

- Education
- Non-Profit
WOVEN & NICE
Woven is a Spring Valley, NY nonprofit running the NICE program (New Training Inclusive Community Environment) in four Rockland County schools. Their team supports students through restorative practices, mediation, and professional development for teachers and administrators.- 4Schools Served
- 4Weeks to Launch
- 1STTime on Upwork

- Healthcare
CareInTouch
CareInTouch is a Bay Area home health agency providing skilled nursing and therapy services to patients referred from hospitals and clinics. With over 100 staff, they operate in one of the most complex and compliance-driven healthcare markets in the country.- 40% Reduction In Billing Errors
- 100+Staff Operations Managed
- 0Missed Compliance Deadlines

- Startup
Sparkle The Cleaning Service
Sparkle The Cleaning Service is a Detroit-area residential cleaning company with 10 years in business, connecting homeowners with vetted, insured independent cleaners through a subscription-based marketplace platform.- 75% Platform Transparency
- 2XPlatform Growth
- 40%Higher User Retention

- Startup
DineMate
DineMate is a Maryland-based dating and connecting platform built around verified profiles, restaurant reservations, and prepaid dining experiences. Founded to bring back authenticity to how people meet and connect.- 60% Time Saved
- 99%System Reliability
- 40%Higher User Retention

- Healthcare
Prior Authorization AI
Prior Authorization AI is a healthcare automation startup building AI-powered tools to streamline prior authorization for Medicare and Medicaid medical transportation providers in New Jersey.- 16Weekly hours saved
- 63%Admin time reduced
- 43%Fewer submission errors

- Education
Grand Central Language Services
Grand Central Language Services provides translation and interpretation for organizations operating in complex, multilingual environments. As demand grew, internal workflows became harder to manage. SoftDoes built a custom platform to streamline coordination, improve visibility, and support scalable operations.- 72%Workflow Reduction
- 48%Coordination Reduction
- 83%Visibility Increase

- Healthcare
FMY Orthodontics
FMY Orthodontics, a multi-location practice in West Tennessee, partnered with SoftDoes to replace a spreadsheet-based financial workflow with a custom web platform. The goal was to simplify how staff present treatment financing while allowing patients and families to review and complete decisions remotely.- 60%Workflow Reduction
- 75%Remote Adoption
- 5Locations Aligned

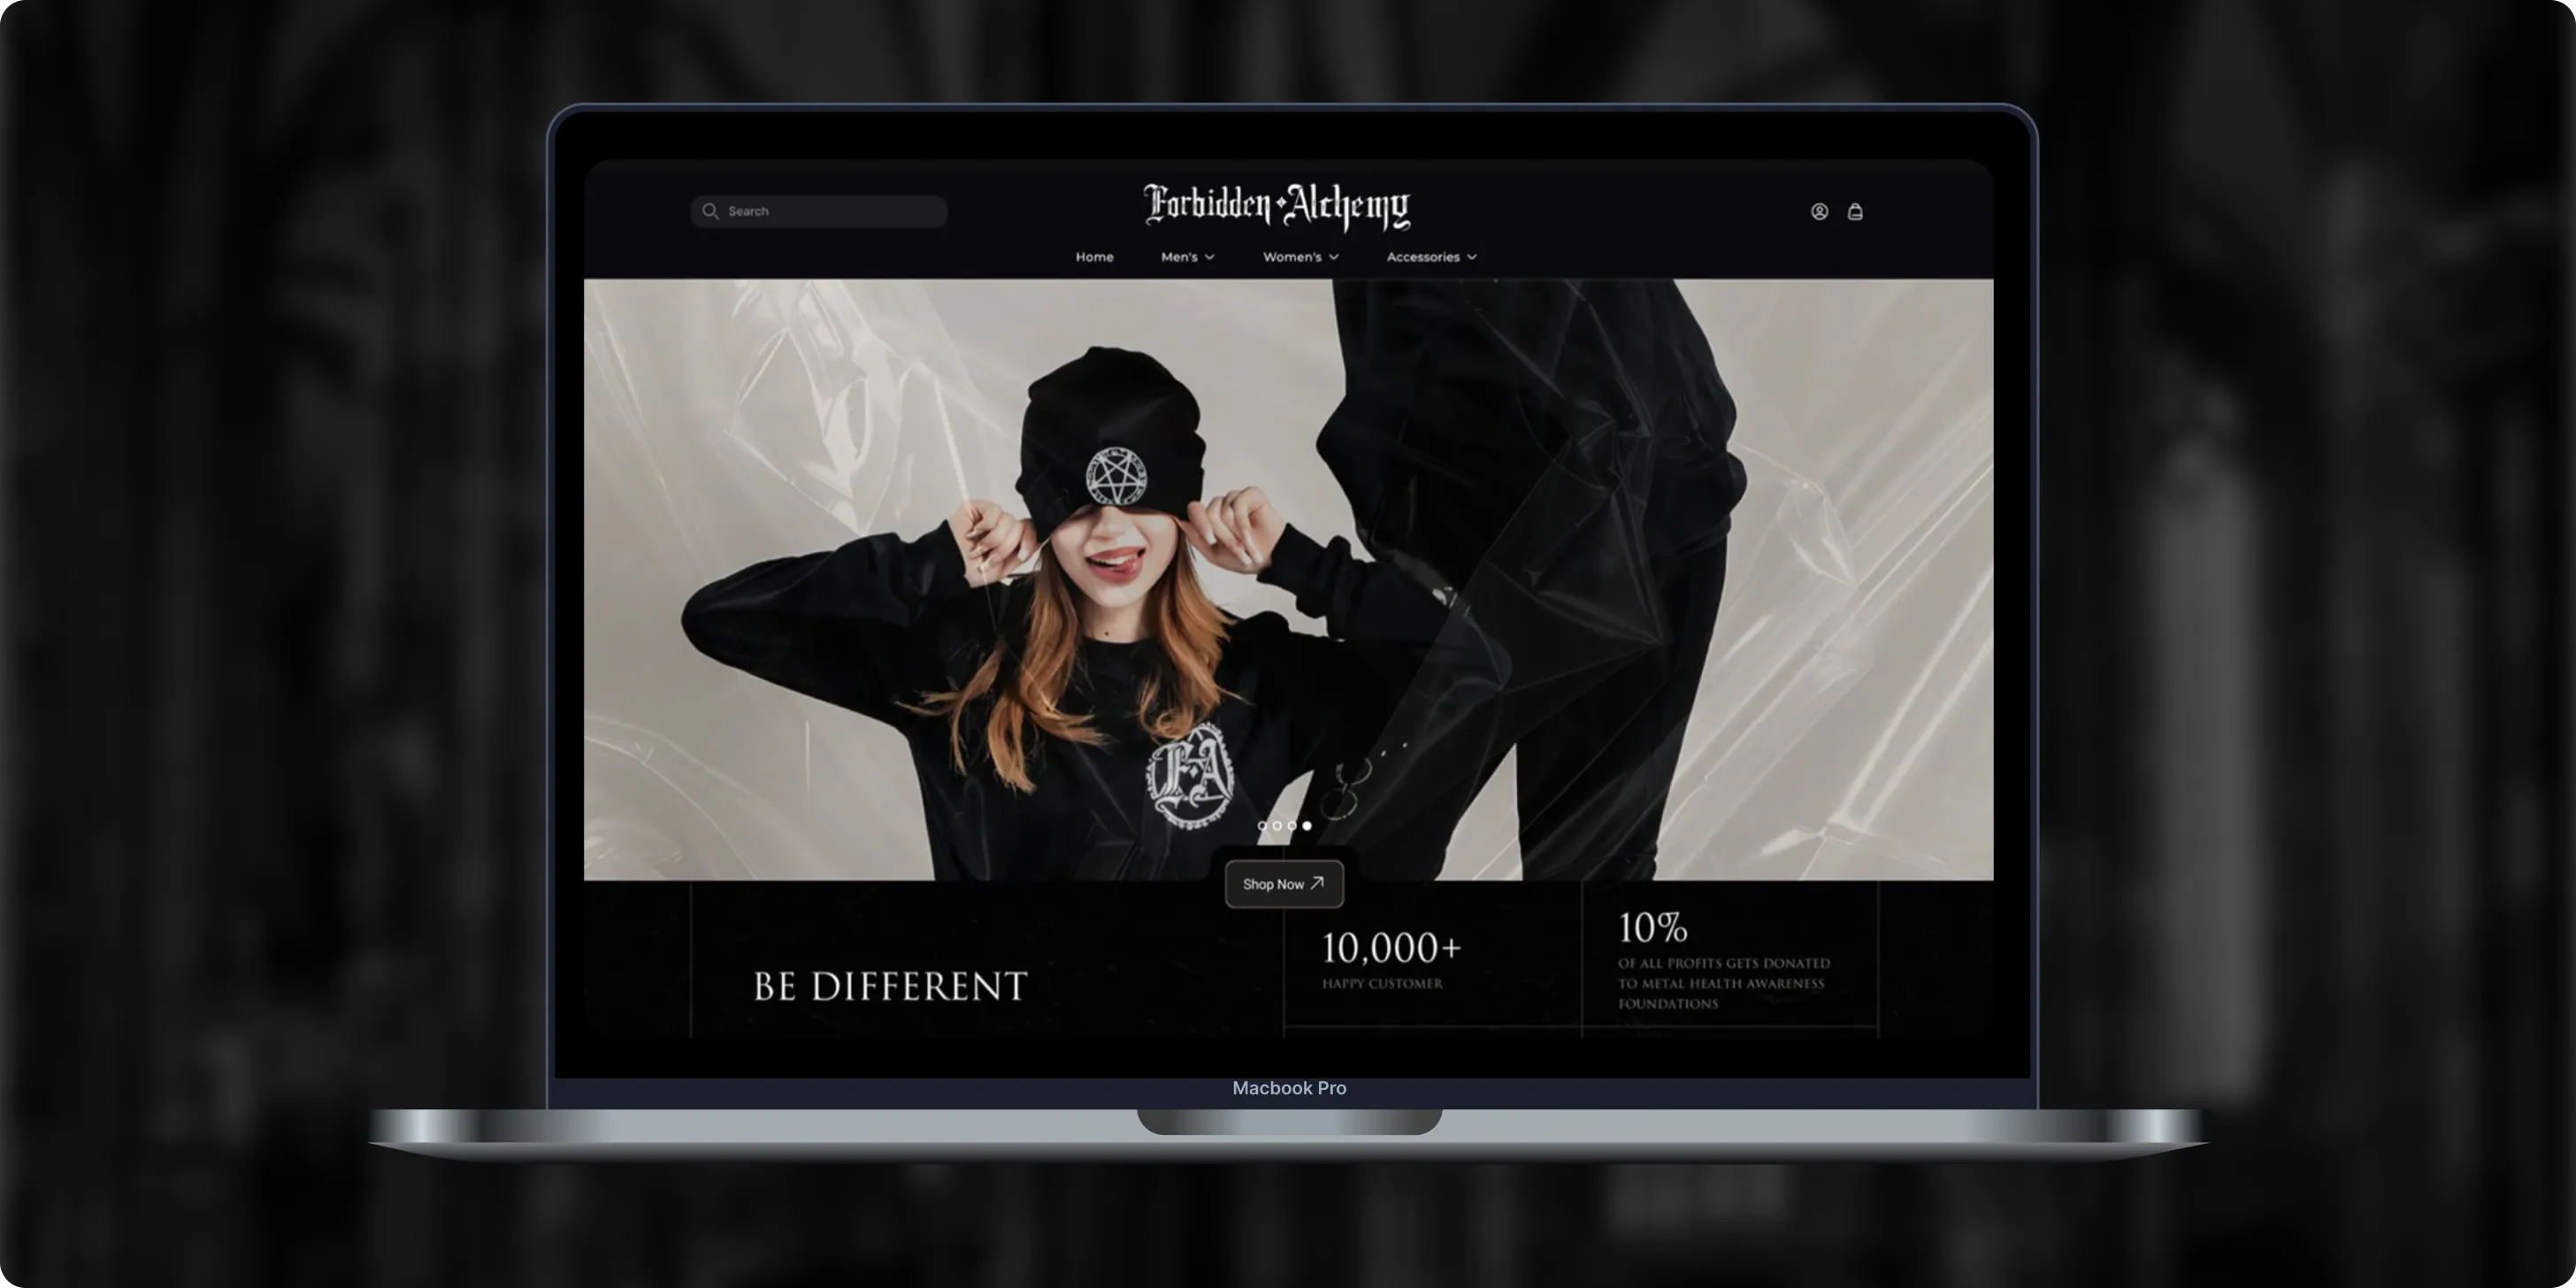
Forbidden Alchemy
Forbidden Alchemy is an alternative fashion brand creating dark, provocative clothing for the metalhead community, with 10% of profits donated to mental health awareness. Its mostly mobile audience struggled with a store that was hard to navigate and weak on functionality.- +44%Revenue Month Over Month
- 86%Design Satisfaction
- 2.8XUser Retention Growth
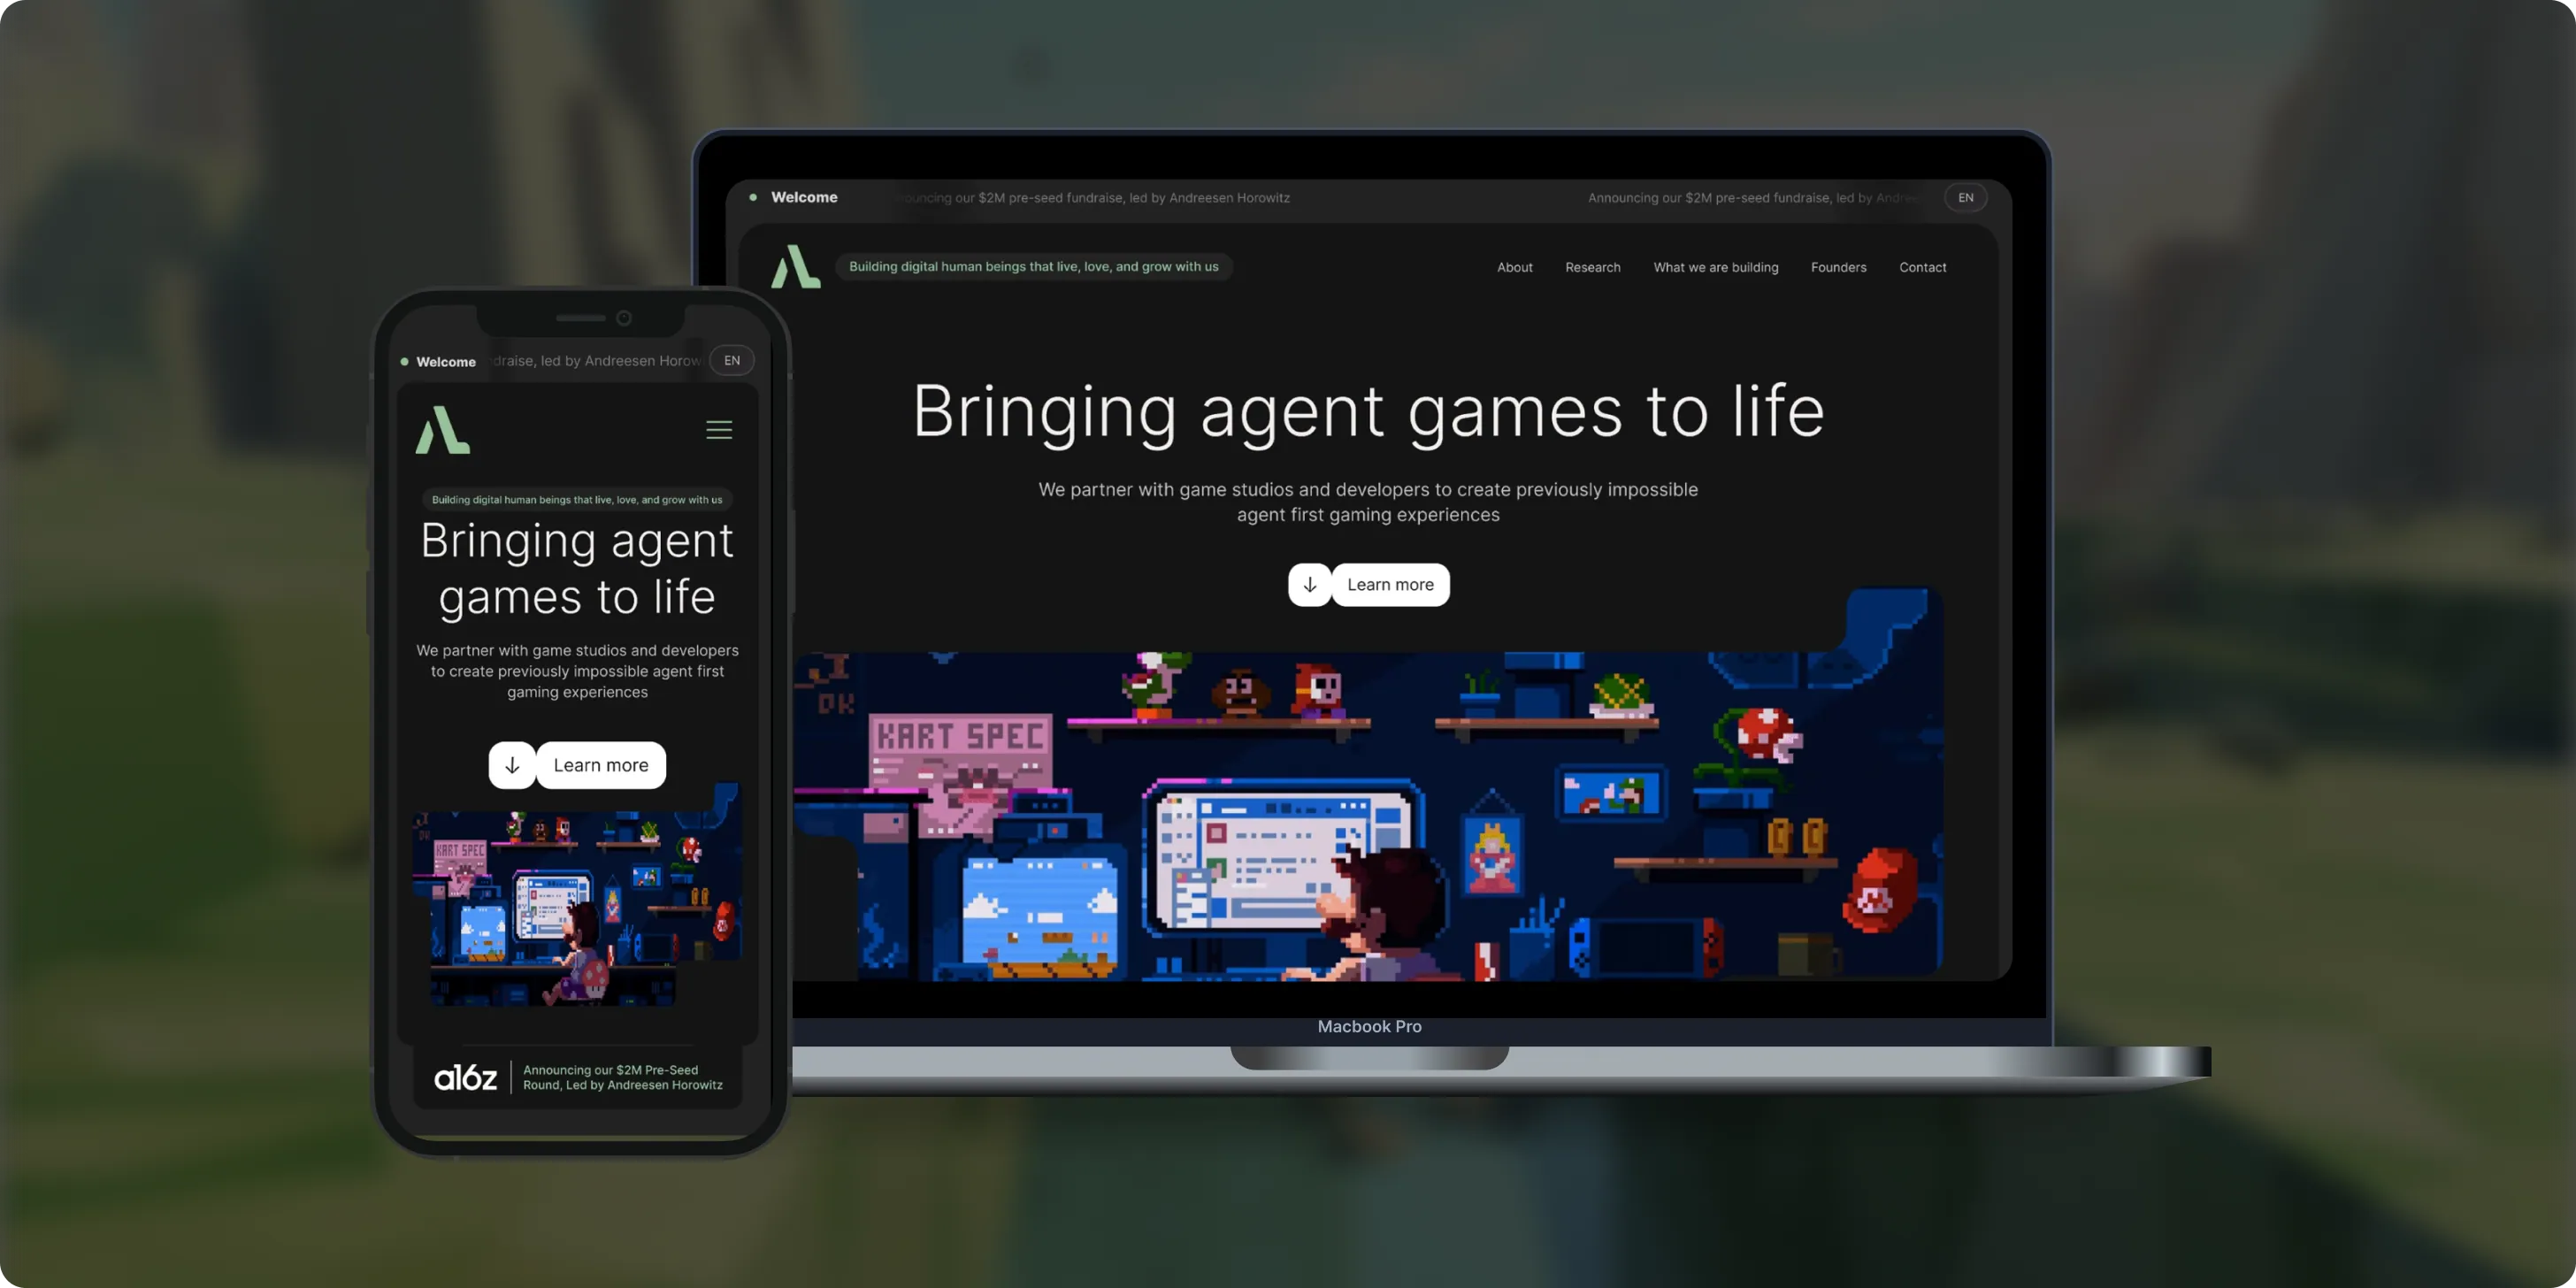
Altera
Altera builds on decades of computational neuroscience research to create digital human beings for gaming. Backed by a $2M pre-seed round led by Andreessen Horowitz, the team needed a landing page that could explain complex agent technology to players, partners, and investors.- 98%Dynamic Customization
- 100%Streamlined Navigation
- $2MPre-Seed Round
- Real Estate
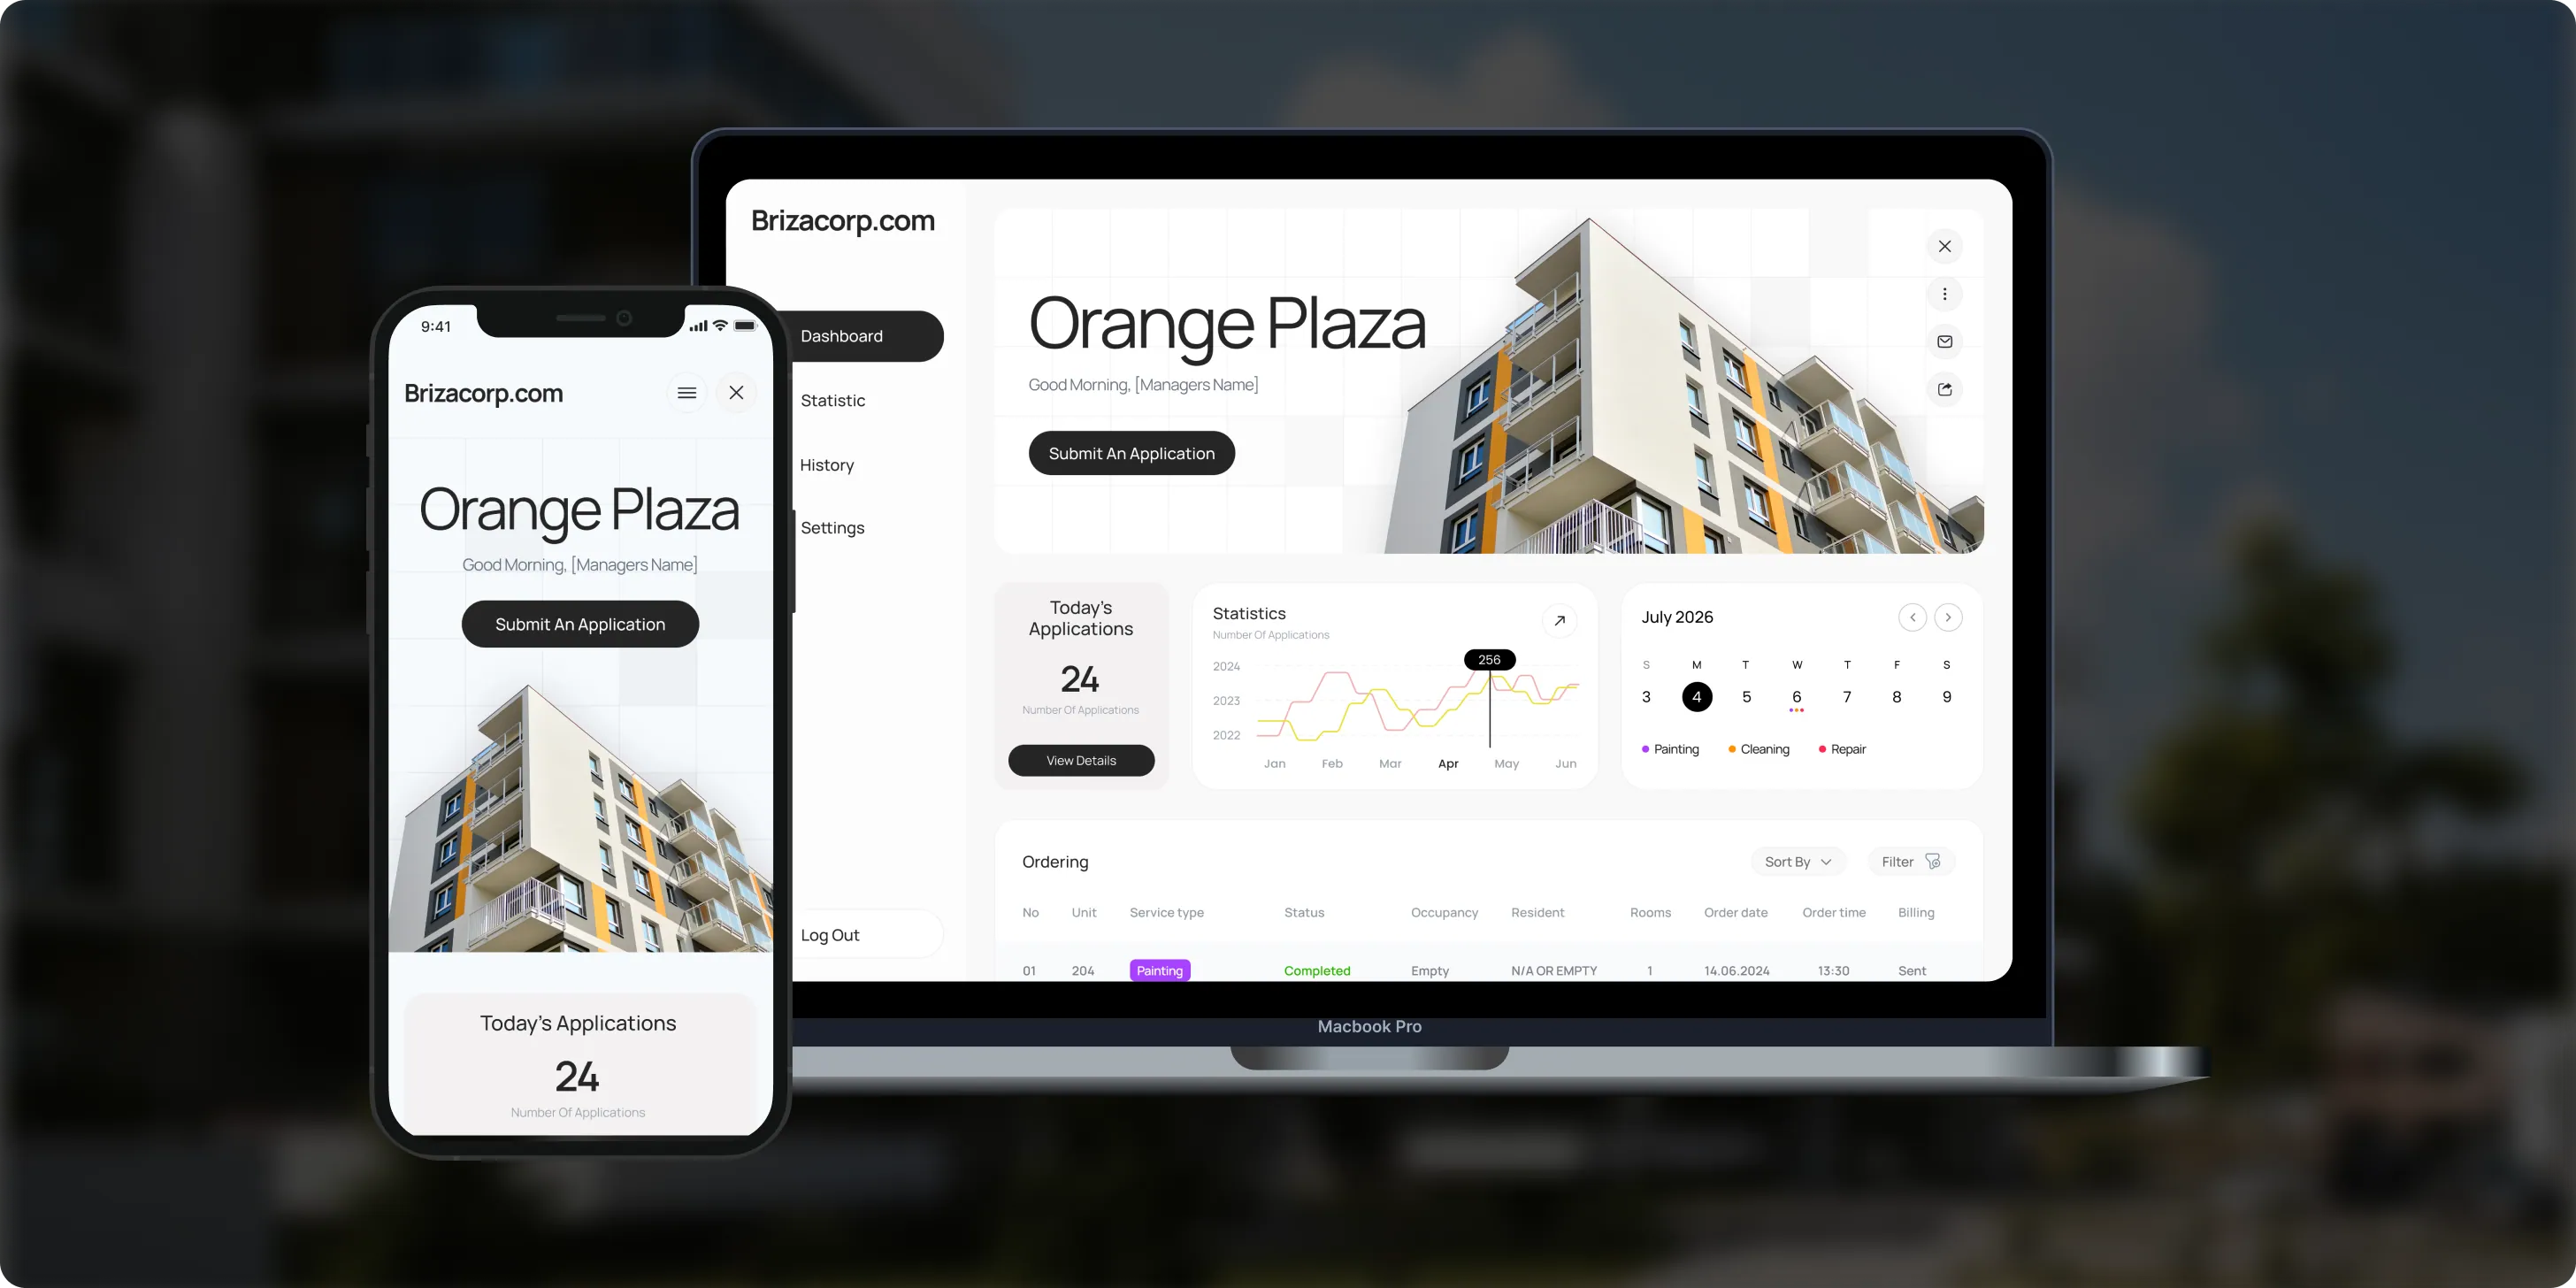
Brizacorp
Brizacorp manages residential properties and coordinates the staff who handle painting, cleaning, and repair requests. Its team tracked work across messengers, phone calls, e-mail, and paper planners, with no single place to manage requests or measure performance.- 98%Application Stability
- 95%Utilization Rate
- 30%Faster Task Completion
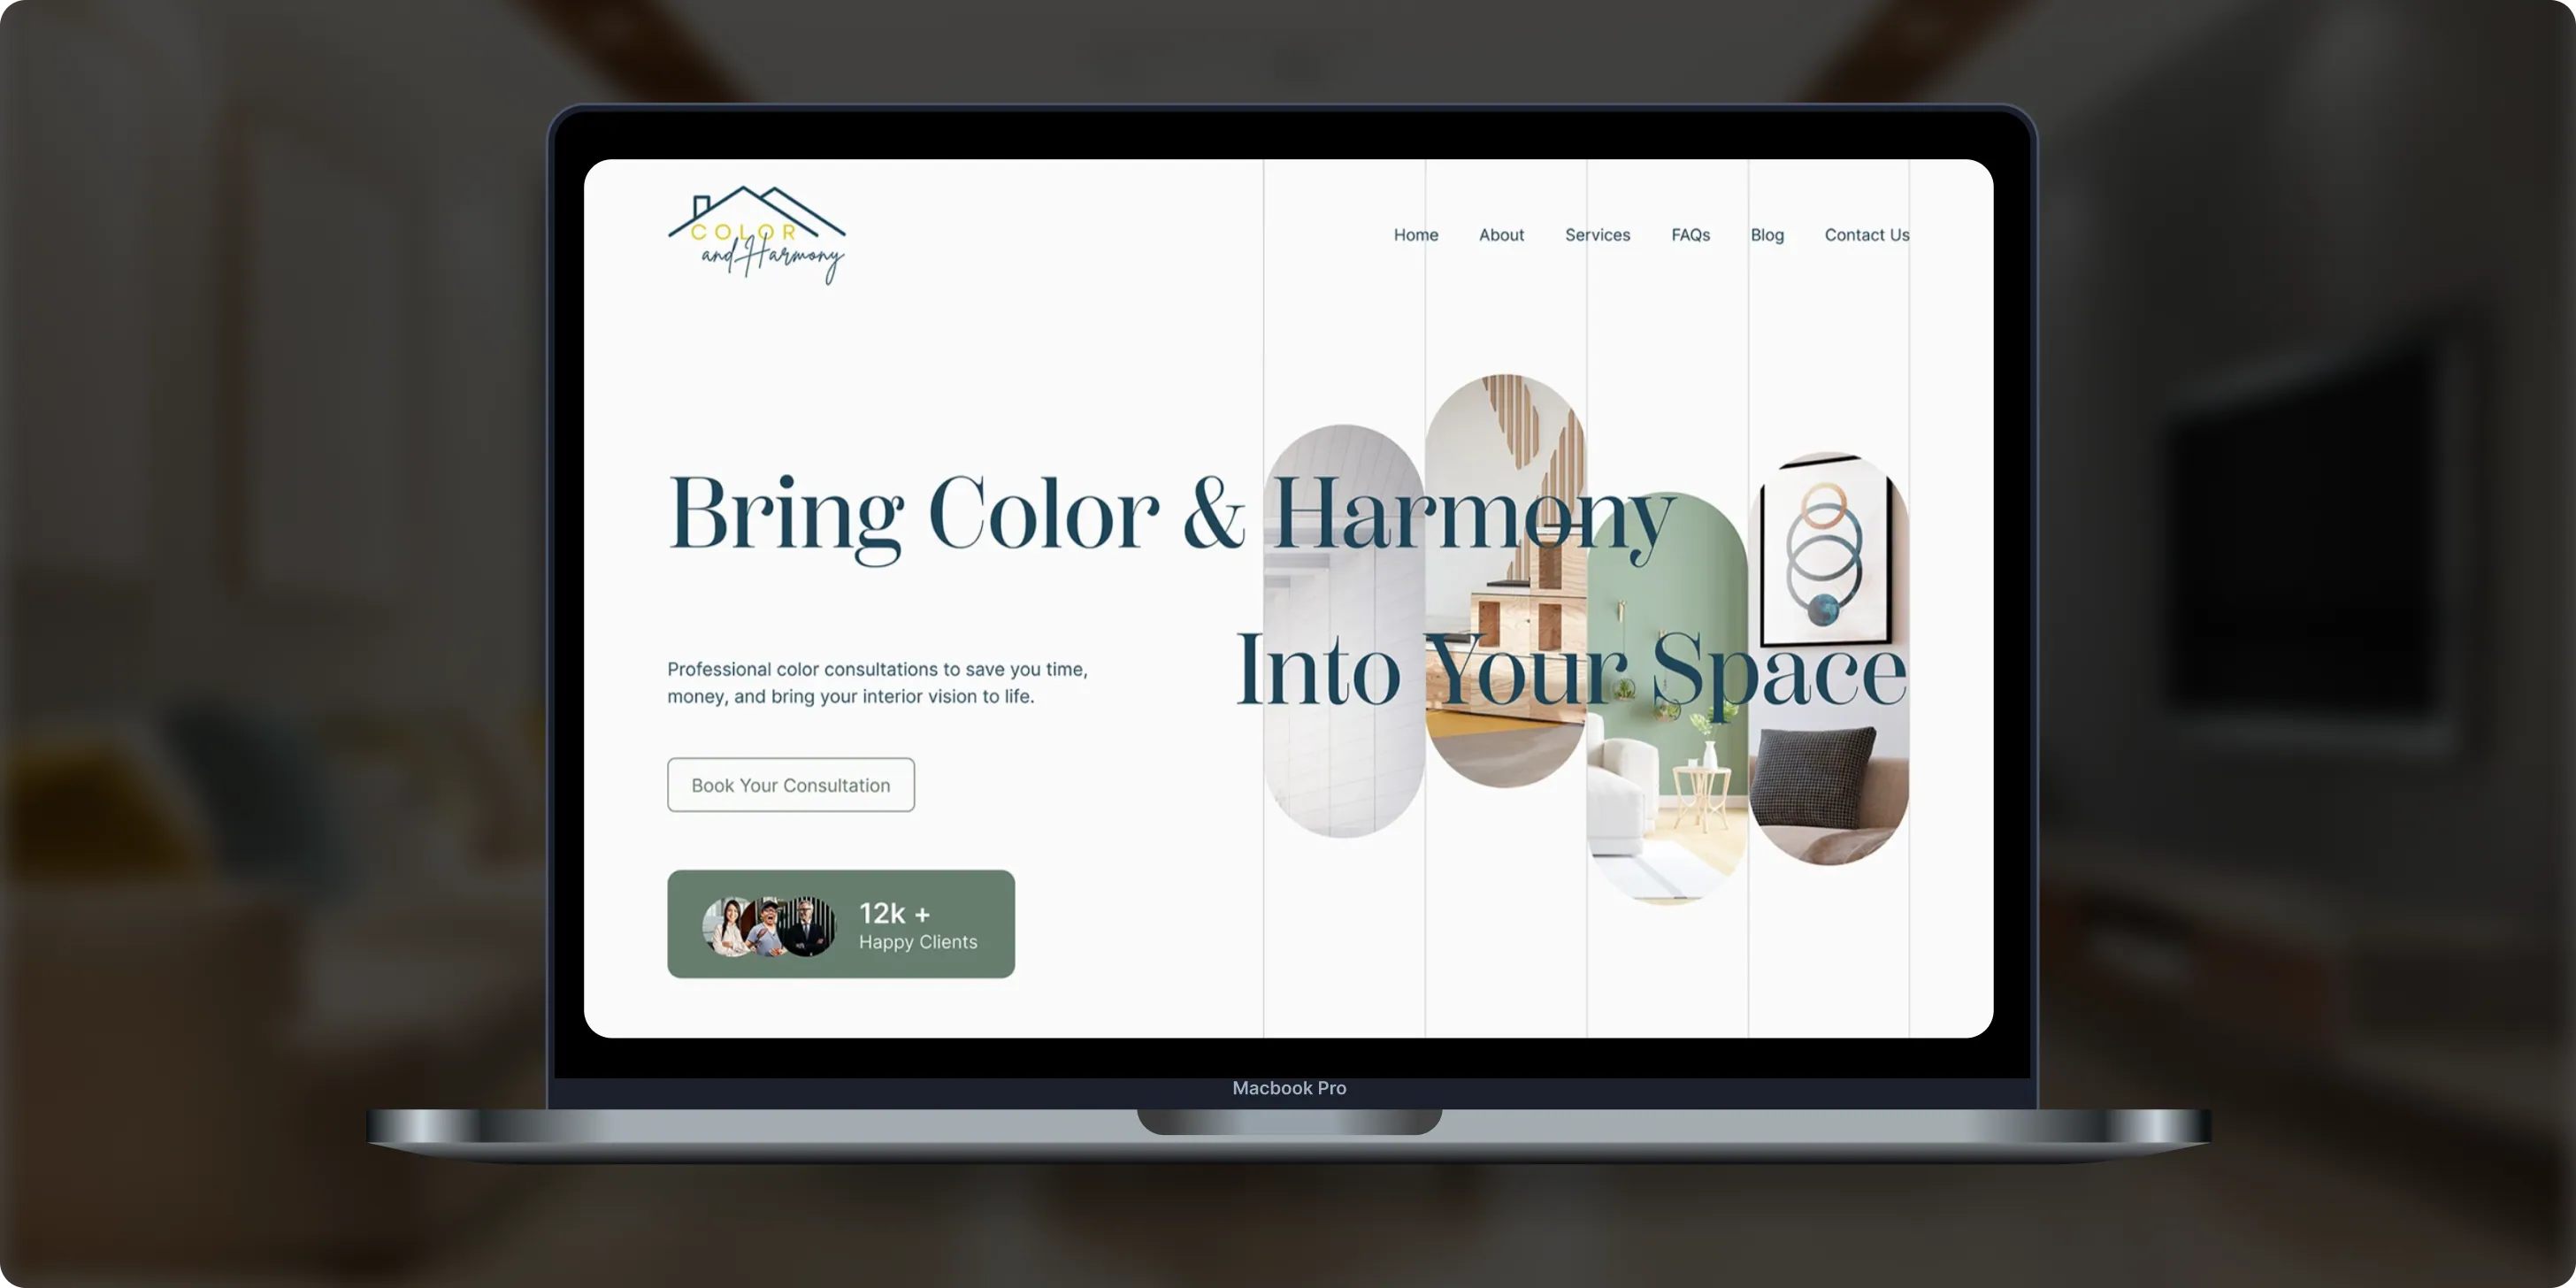
Color & Harmony
Color & Harmony is a Kentucky-based color consulting studio led by certified color strategist Diana Cartaya. The studio needed a website that reflects its refined aesthetic, showcases its portfolio, and explains a science-based color process in simple language.- 45%Conversion Rate Increase
- 50%Higher User Engagement
- 2Months to Launch
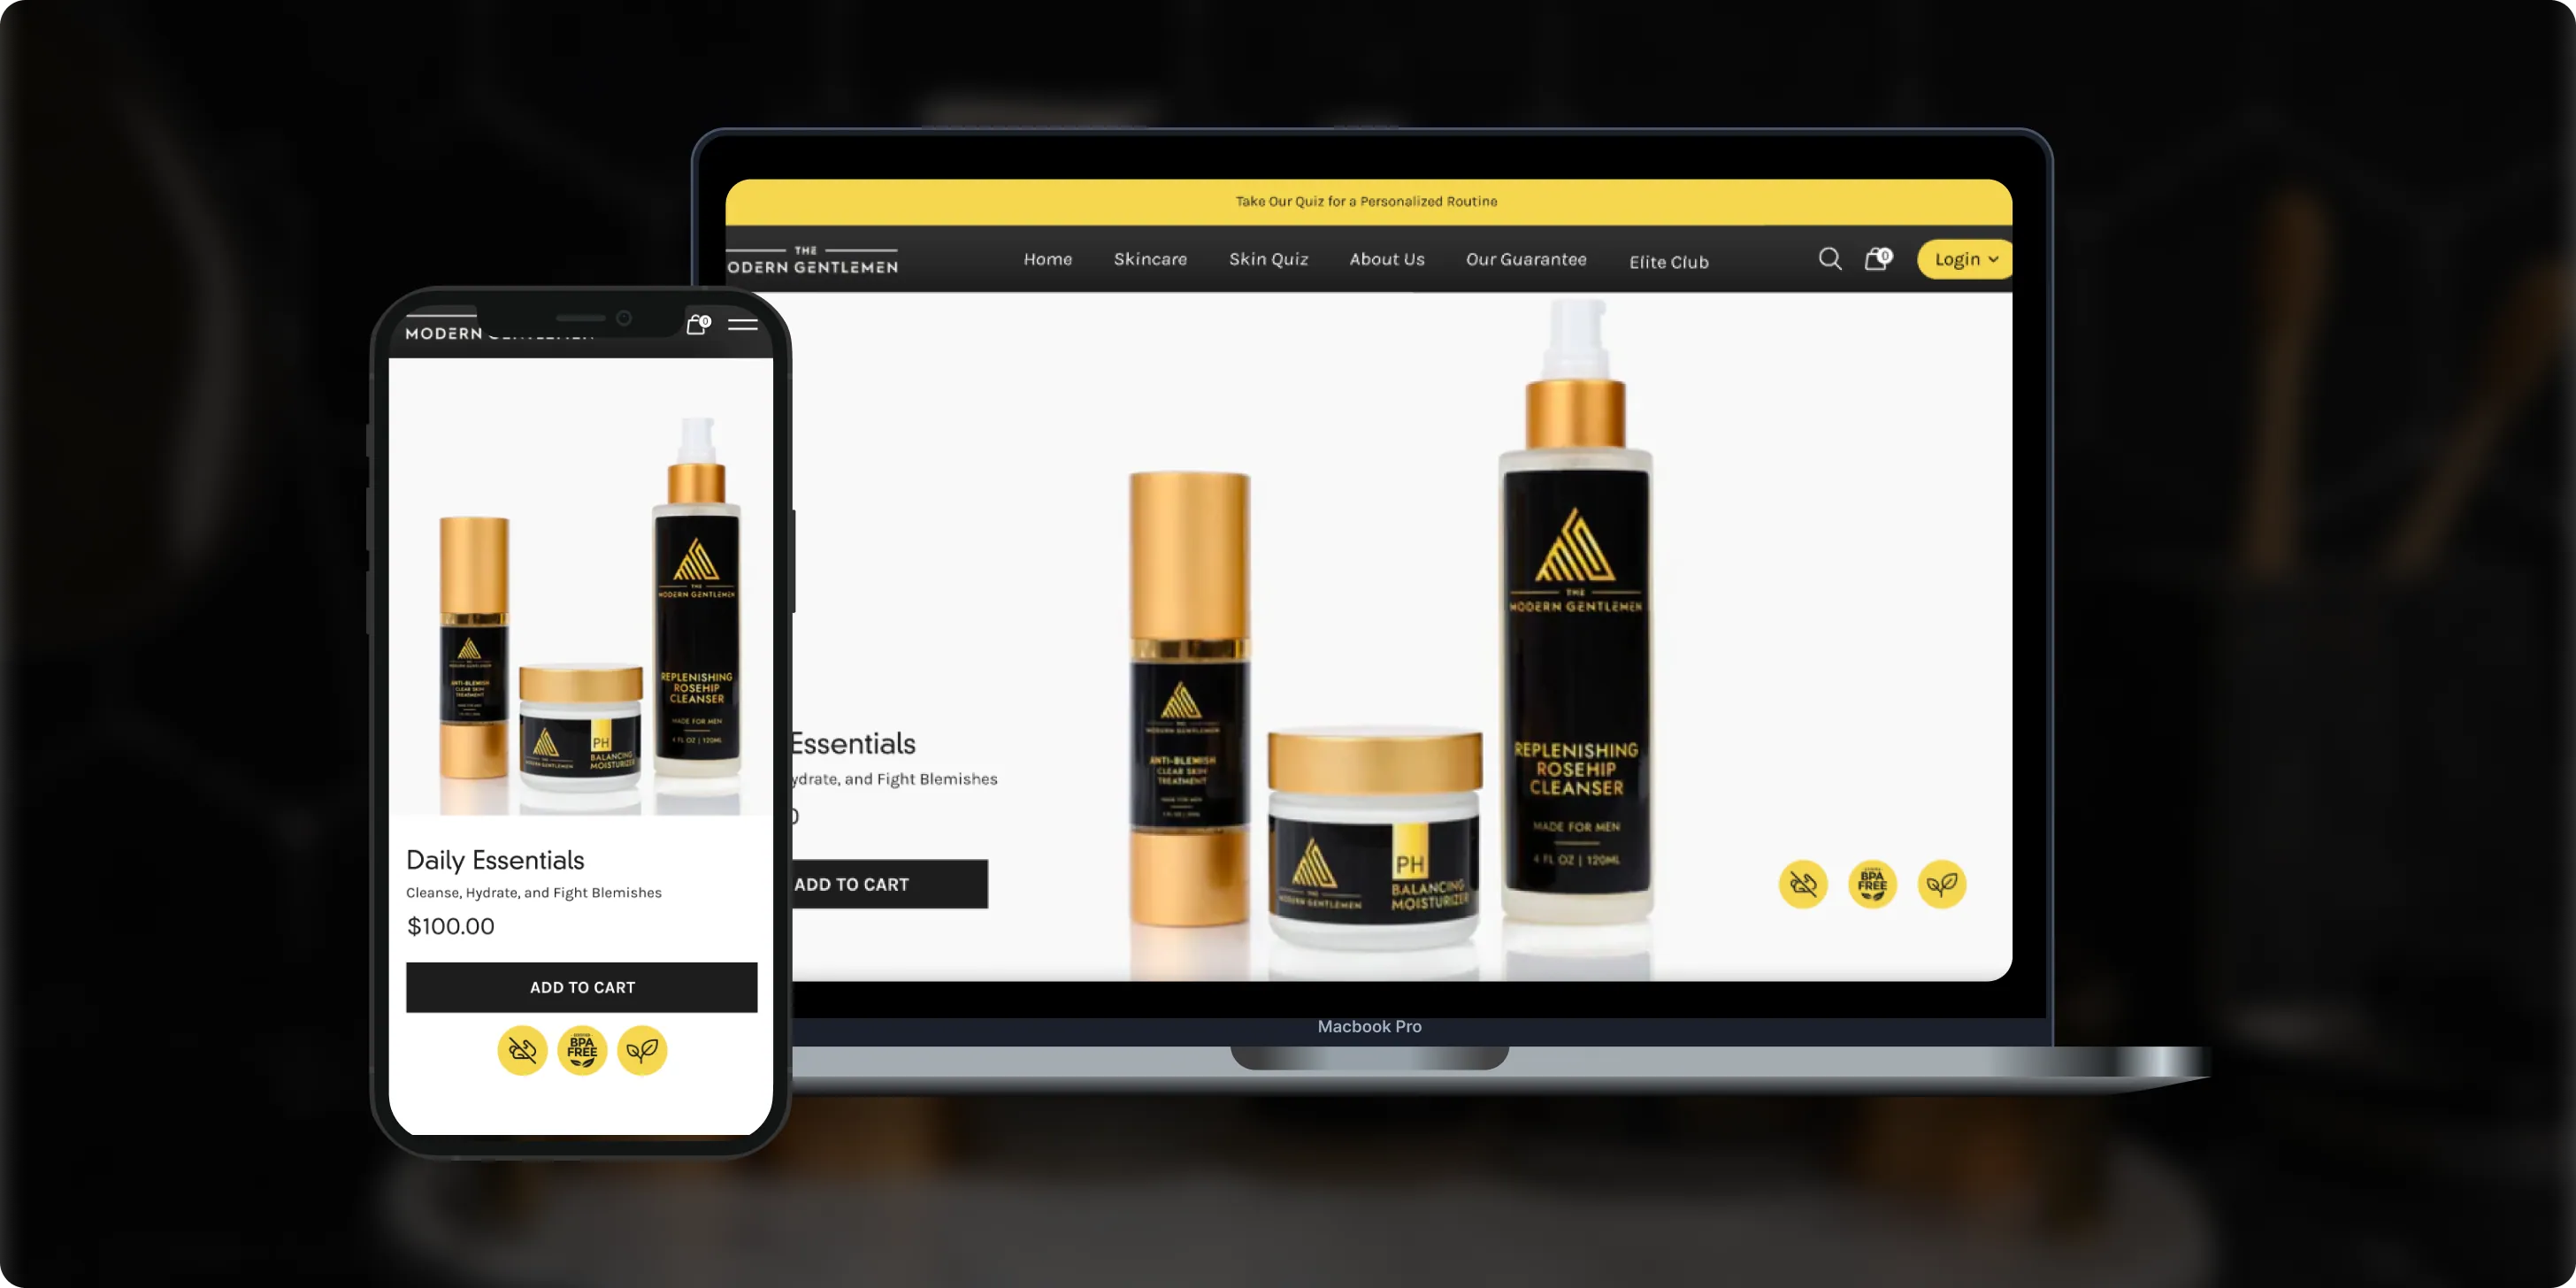
The Modern Gentlemen
The Modern Gentlemen sells premium men's skincare featured in Men's Health, GQ, and Men's Journal. Its customers wanted an efficient routine, but generic product suggestions and limited skincare knowledge made choosing the right products hard.- 30%Increase in Conversions
- 25%Higher Customer Retention
- 92%Mobile Purchases
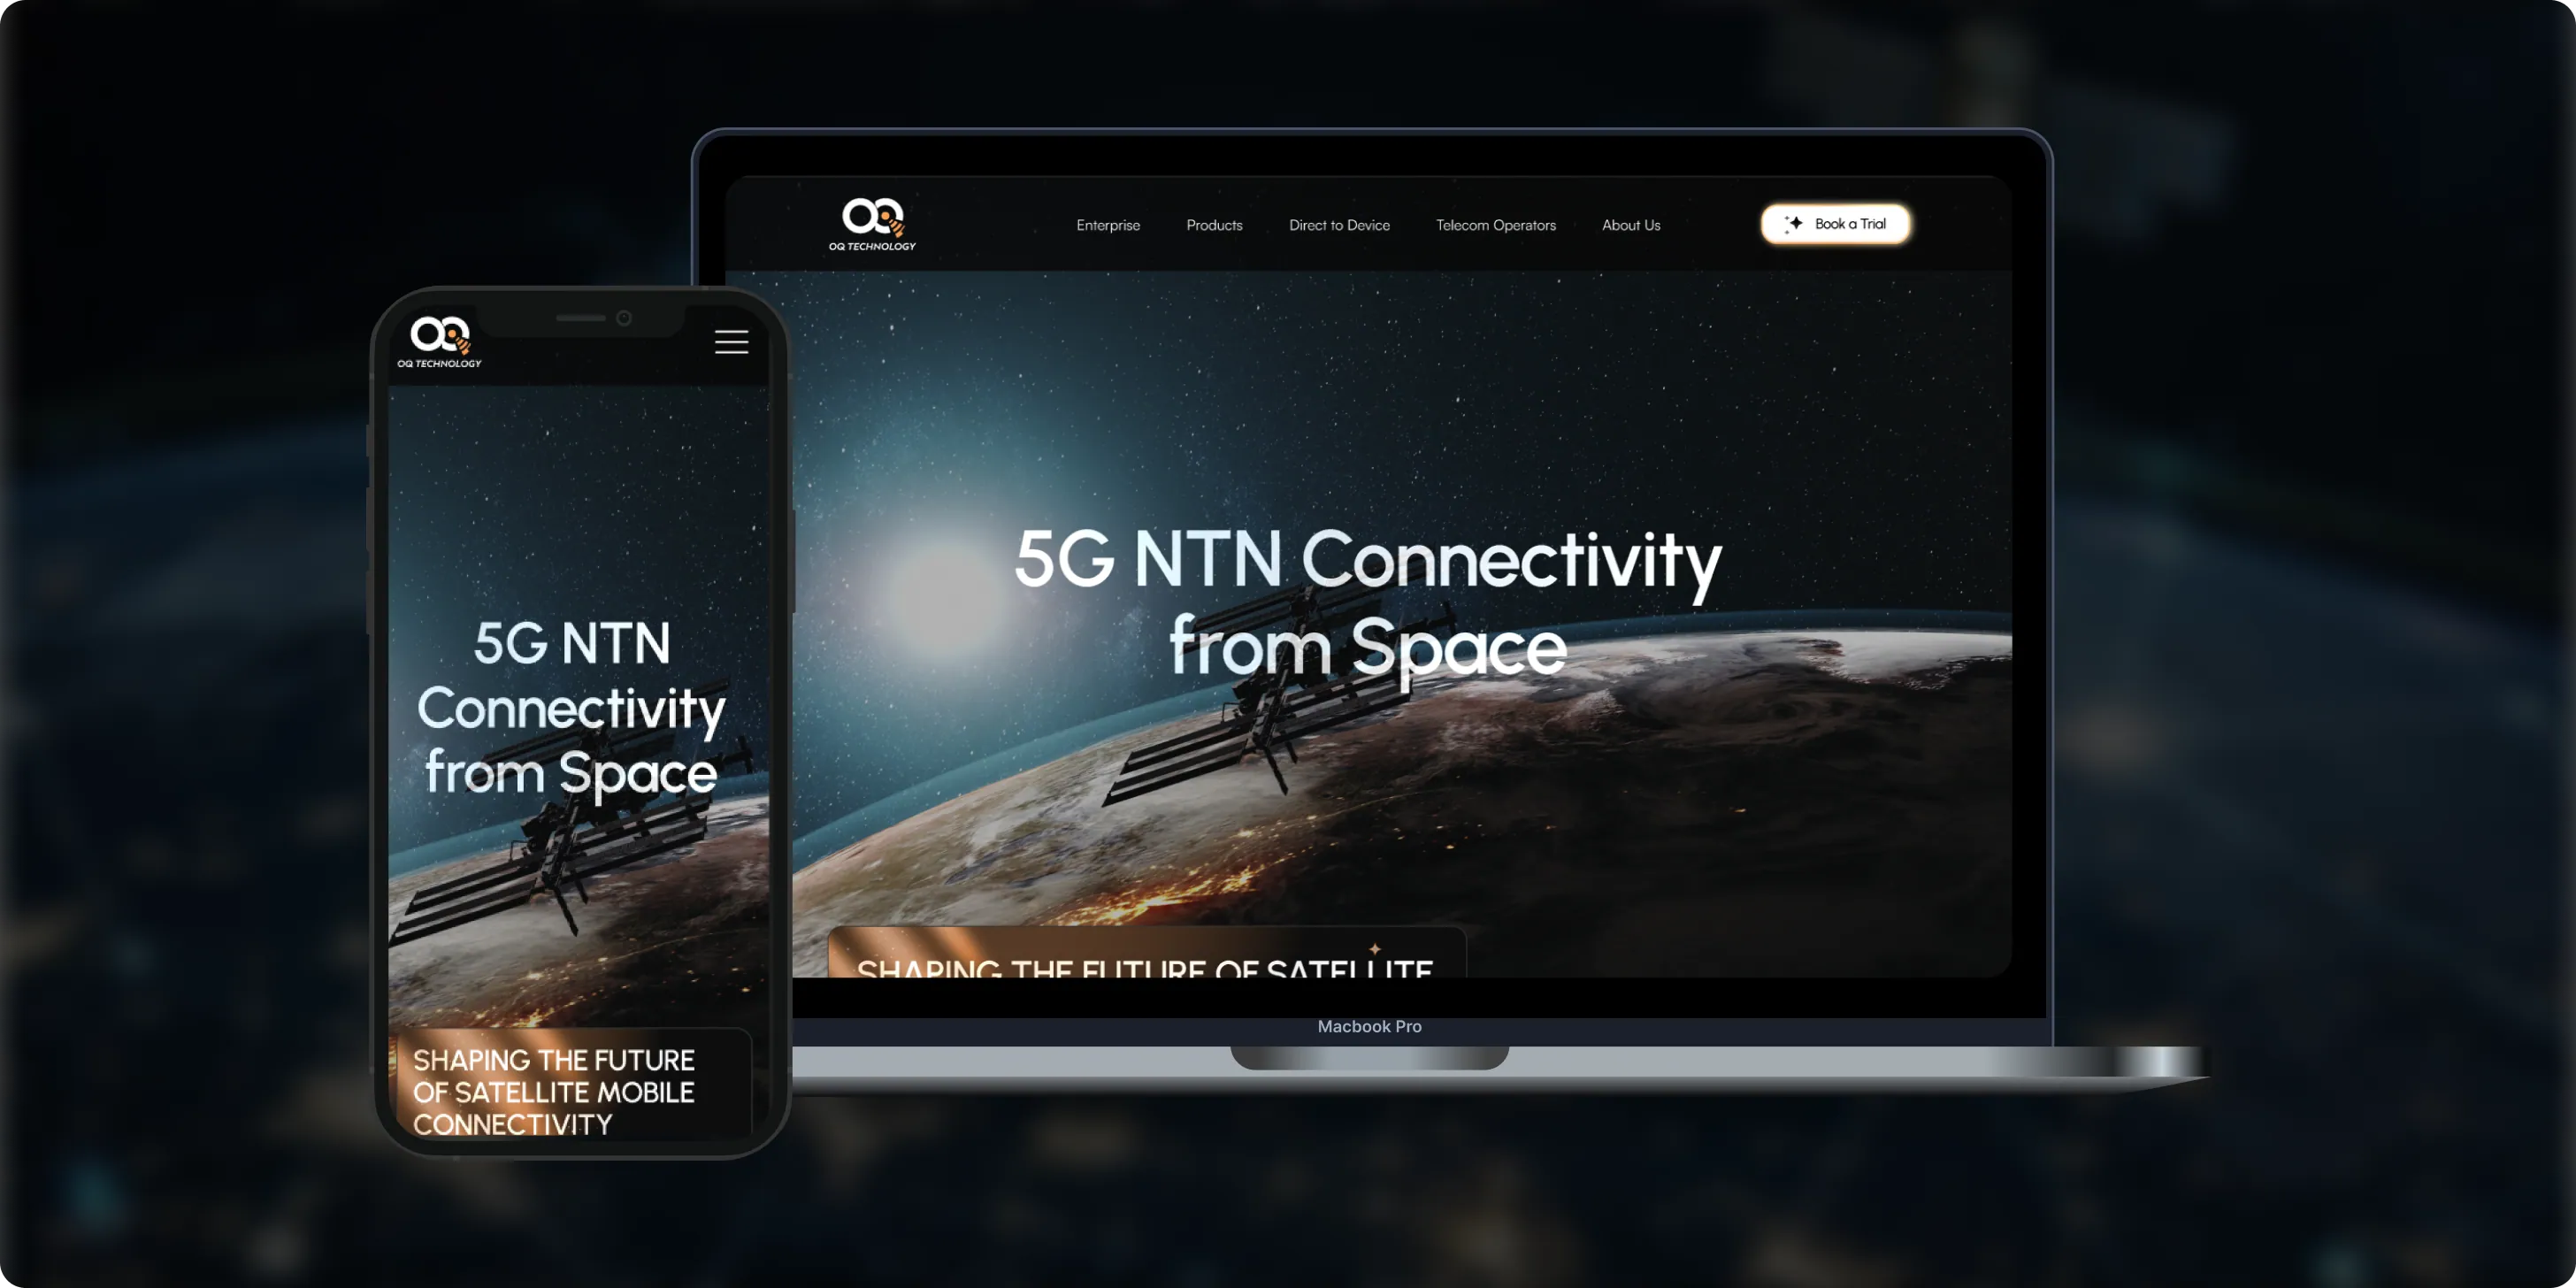
OQ Technology
OQ Technology connects IoT devices, machines, and people anywhere on the planet through its satellite network, serving energy, maritime, logistics, agriculture, and mobile operators. Its website made it hard to explore products and reach pricing plans.- 4Pricing Plans Clarified
- 3Dedicated User Flows
- 1Unified Platform
- Real Estate
- Finance
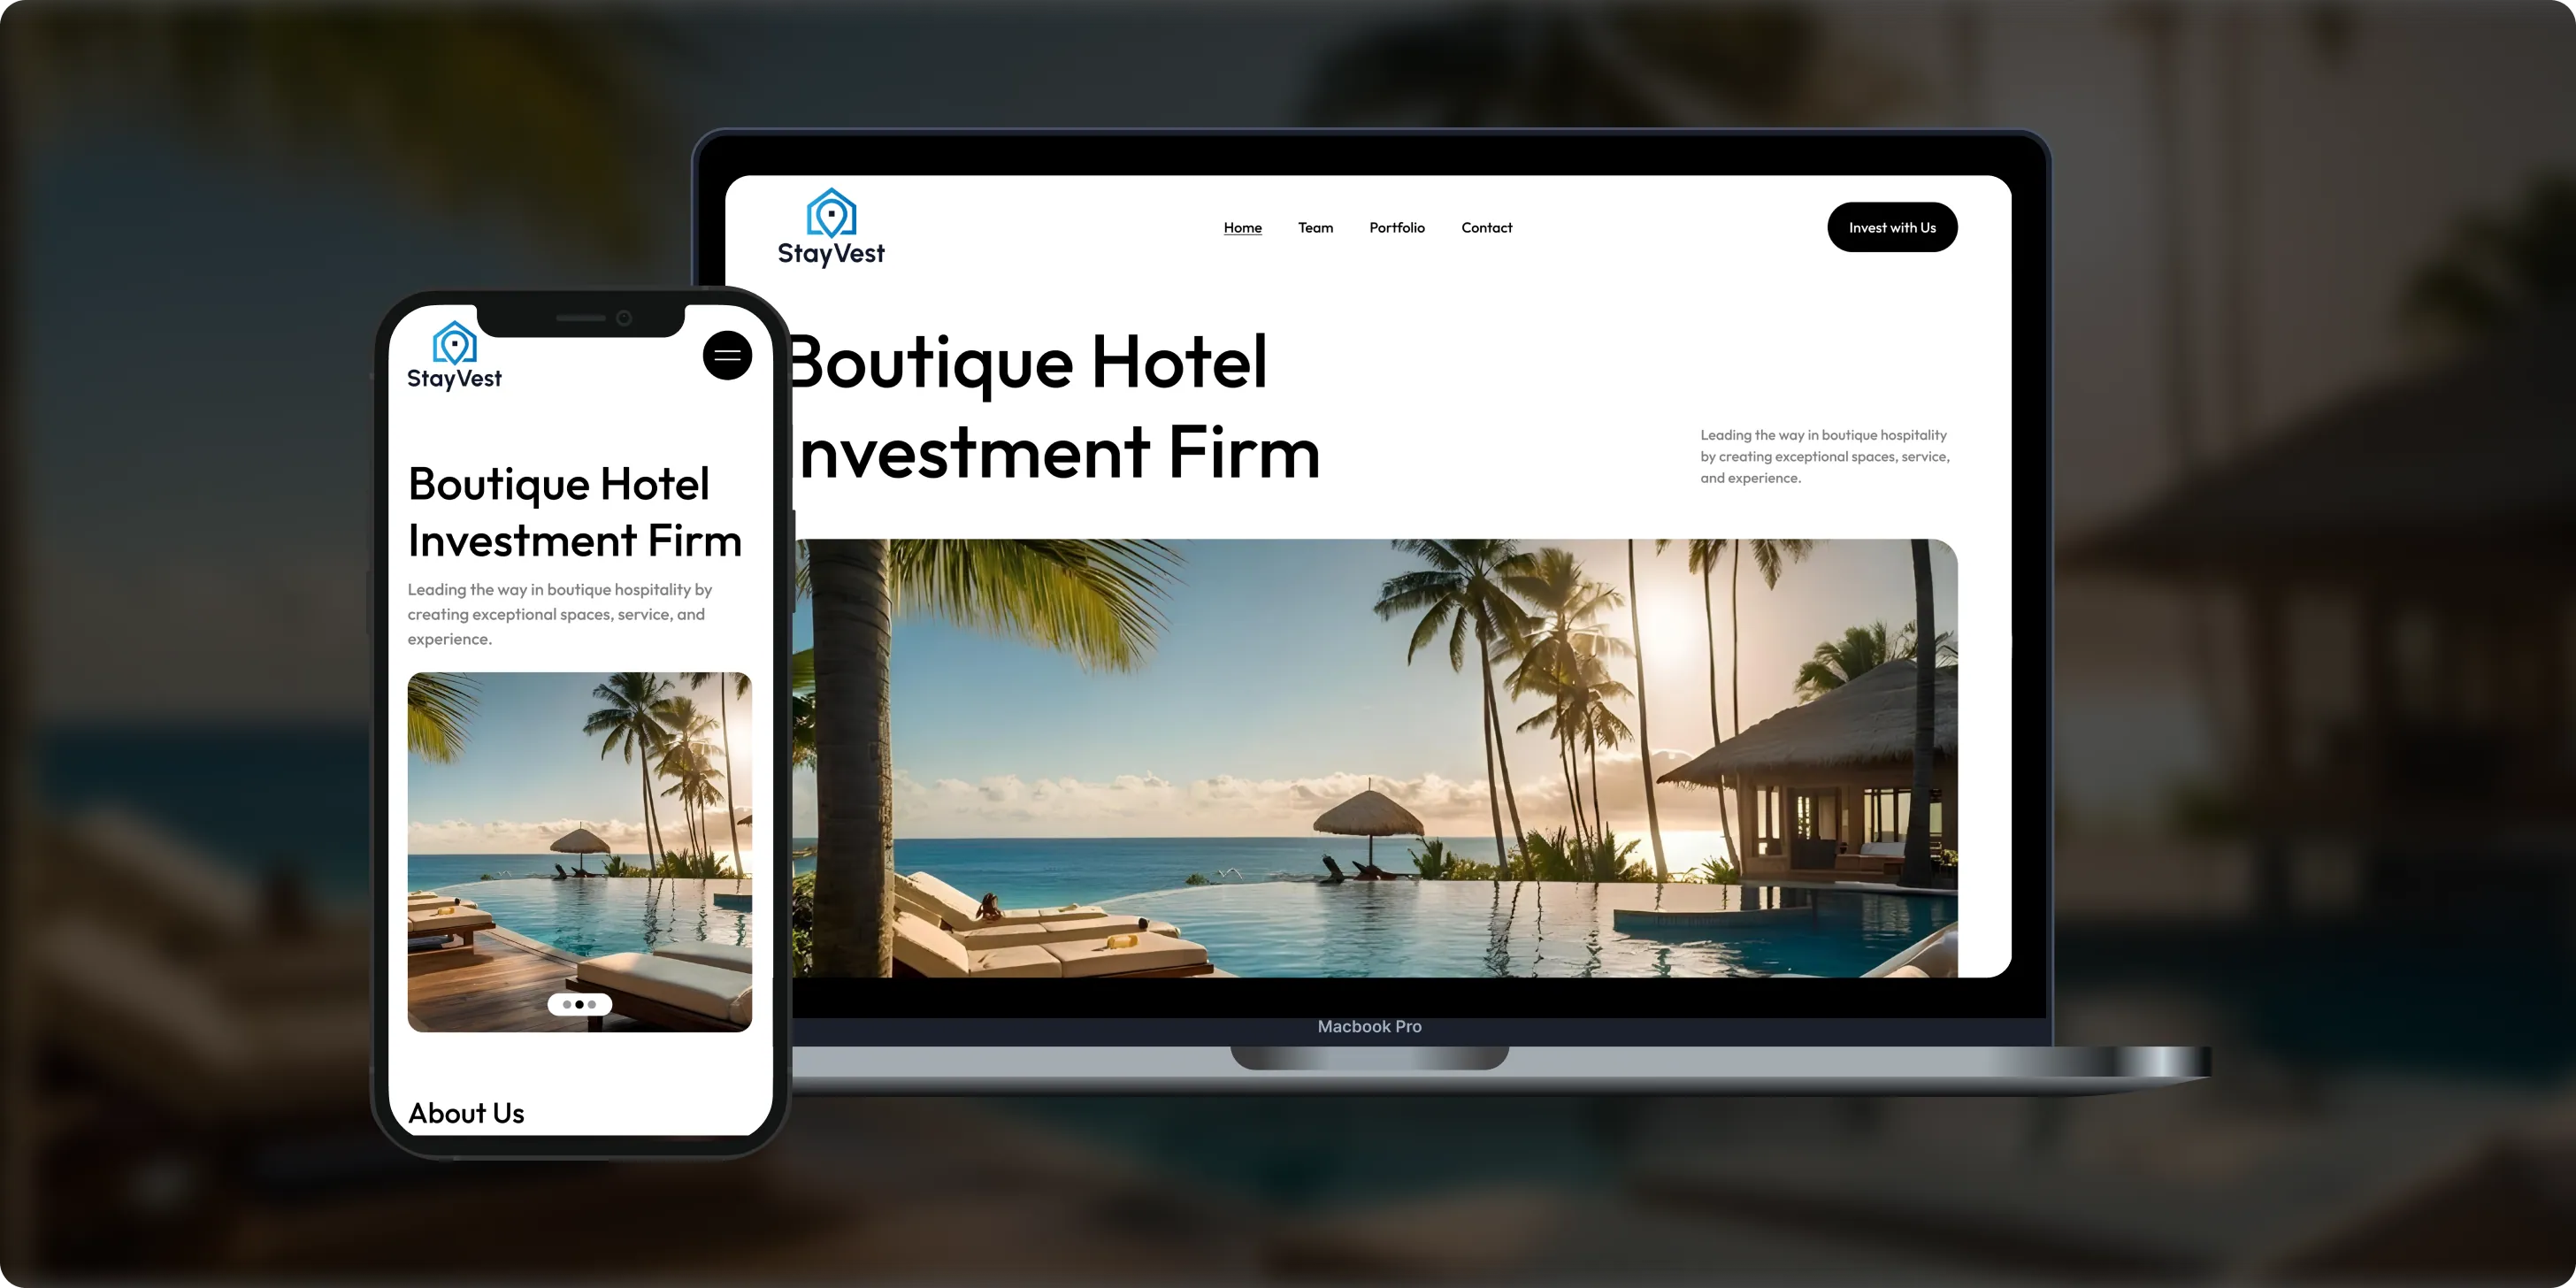
Stay Vest
Stay Vest is a private real estate investment firm that acquires, renovates, and operates boutique hotels for cash flow, tax benefits, and equity gain. It needed a platform that explains its strategy and earns the trust of passive investors.- 1,500+Guest Stays
- 200+Rooms Managed
- 5States Covered
Bokeyno Motorsports
Bokeyno Motorsports is the leading mobile installer of vertical doors for high-performance cars. This Shopify website isn’t just about services—it’s a bold statement of power, style, and expertise. With a sharp layout, strong visuals, and real-world case studies, the site delivers all the information car enthusiasts need to book confidently and instantly.- 54%Booking Requests
- 43%Lead Conversion
- 32%Qualified Inquiries

ai document processing platform
A comprehensive talent solution designed to help companies attract, hire, and retain top talent more effectively. The platform combines AI-powered recruitment technology with employee financial wellbeing programs, enabling smarter hiring decisions while supporting employees’ financial stability and long-term engagement.- 62%Faster Processing Time
- 78%Less Manual Work
- 35%Improved Accuracy

WHAT CLIENTS SAY
Independently verified reviews from real clients on Clutch.co


Client Story
Real feedback from
FMY Orthodontics
“Their perseverance and solution-oriented mindset. SoftDoes consistently found ways to make things work, added features we had not originally envisioned, and never became frustrated. It felt like working with a true partner who cared about the success of our practice.”
Dan Merwin
DDS, MS -- President, FMY Orthodontics

Client Story
Real feedback from
Prior Authorization AI
“Every time I sent a request, if there was anything that didn't work, they were able to turn it around quickly. Even when there were no updates yet, they always reached out to let me know they were working on it.”
Joseph Oluwo
Founder of Prior Authorization AI


Client Story
Real feedback from
WOVEN
“What stood out most was their commitment to understanding our needs before presenting solutions.”
Danna Pastran
Administrative Operations Manager, WOVEN

Client Story
Real feedback from
Grand Central Language Services
“The site performs as intended and provides the foundation for our company's digital presence.”
Joe Goldstein
QA Manager, Grand Central Language Services


Client Story
Real feedback from
DineMate
“They go above and beyond.”
Eric Snead
CEO, DineMate "Dating Connecting Platform"
Why they Choose SoftDoes
- 01SENIOR ENGINEERS, NOT LAYERS
Every project is led by senior engineers and solution architects who have designed and shipped complex digital banking, payments, and regulatory systems for financial institutions. They can read regulatory guidance, internal policies, audit findings, and risk assessments - then translate them into concrete data models, workflows, and integration patterns. Your product, IT, risk, and compliance leaders work directly with the financial software development team building your platform, without layers of account management diluting context. Our engineers are comfortable discussing ledger structures, posting rules, ISO 20022 messages, SCA flows, and core-banking constraints in detail with your teams. This depth reduces the misinterpretations that otherwise surface late in user acceptance testing or regulatory reviews, when they're most expensive to fix.
- 02PREDICTABLE DELIVERY
SoftDoes aligns phased releases with regulatory timelines, change advisory board (CAB) processes, release windows, and typical year-end or quarter-end change freezes common across the banking industry. We use production-like staging environments with realistic anonymized or synthetic data to validate integrations and stress workflows before go-live. Specifications and acceptance criteria are expressed in terms of banking workflows - payment journeys, collections, dispute handling, loan processing - not abstract user stories. We coordinate dependencies across client security, infrastructure, vendor management, and third-party providers such as card processors and KYC vendors. This predictability is essential when a platform touches customer money, regulatory reporting, and daily branch or call center operations.
- 03BUILT TO LAST PAST LAUNCH
Architecture is shaped around stable domain boundaries - customers, accounts, ledgers, payments, cards, loans, compliance - with documented APIs between them. Robust logging, metrics, and end-to-end transaction tracing let teams follow a payment, card authorization, or loan posting from entry through settlement and reporting without guesswork. Idempotent processing and replay mechanisms handle retries and network glitches without mis-postings or duplicate entries - because a software bug can create real monetary loss in banking systems. Maintainability practices include peer-reviewed code, automated tests for critical financial logic (interest accrual, fee calculations, foreign exchange, rounding), and CI/CD pipelines with security testing integrated throughout. These foundations let you scale volumes, add new products, or connect new partners without rebuilding the platform from scratch.
- 04NO BABYSITTING REQUIRED
SoftDoes plans for handover from the beginning: admin consoles, runbooks, and documentation are built for your product, operations, and IT teams from day one. Intuitive configuration UIs let bank staff manage users and roles, limits, product parameters, cut-off times, and reference data - with proper governance and audit trails. Clear system boundaries and observability mean your internal IT and support teams can troubleshoot issues confidently without relying on external developers for every incident. We offer ongoing support and evolution for institutions that want it, but every system is intentionally designed to avoid vendor lock-in for routine changes. This independence matters for regulated banking institutions that must own their controls and remain accountable to regulators.
How we work with your quality team
This is how SoftDoes partners with you from first conversation through long term support.
Experience Across Retail, Commercial, and Digital Banking
We build software for financial institutions where security, regulatory compliance, and always-on reliability are non-negotiable.
Dental Practices
Orthodontics
Oral Surgery
Specialty Dentistry
Dental Service
Complex systems, integrations, and internal platforms built to evolve. We step in when off-the-shelf tools stop being enough.
Healthcare
From first version to real traction without painting yourself into a corner. Built for speed now and hard decisions later.
Finance
Systems designed around controls, traceability, and change management. Built so audits don’t become fire drills.
Startups
Infrastructure software built for long timelines and high stakes. Reliable systems for assets that can’t afford guesswork.


Frequently Asked Questions
Everything you need to know about working with SoftDoes. Can’t find an answer?
How long does a custom banking software development project usually take?
Timelines typically range from a few months for a focused module - such as digital onboarding or a payments hub - to 9–18 months for a full digital banking platform spanning multiple products and channels. Integrations with core banking, card processors, KYC providers, and payment rails, plus security and compliance reviews, heavily influence duration. Development typically follows a multi-stage lifecycle from concept to launch, and vendor contracts, internal governance, regulator expectations, and decision-making speed often affect schedules as much as engineering work. The development process includes analysis, design, and deployment stages, each with its own validation checkpoints.
How do you handle integrations with our core banking system and third-party providers?
SoftDoes uses APIs, message queues, ISO 20022 and other financial messaging standards, and secure batch or file exchanges depending on what your stack and policies support. We design clear data ownership boundaries, synchronization patterns, idempotency, and reconciliation processes for money-moving data flows - because banking applications depend on various integrated systems for comprehensive services. APIs enable real-time interaction between banking systems, and API integration reduces data silos in banking operations. We have experience integrating with common cores (Temenos, FIS, Fiserv, Jack Henry, Finastra, Mambu), payment rails, card processors, KYC/AML tools, and internal legacy systems without disrupting daily operations.
How do you ensure security and regulatory compliance?
Security must be prioritized from the start of software development, not added at the end. We implement data encryption in transit and at rest, key management, tokenization of sensitive data, fine-grained access control, multi-factor authentication, and tamper-proof audit logs. Our practices align with control sets used in PCI DSS, SOC 2, ISO 27001, PSD2/SCA, GDPR, and DORA, tailored to each client's jurisdiction and regulatory context. We collaborate with your security team on threat modeling, code reviews, and penetration testing, and support responses to auditor or regulator questions where needed - because financial systems are high-value targets for cyberattacks and data security measures must be integrated throughout the software development lifecycle.
Who owns the source code and intellectual property?
Clients own the custom banking software source code, configurations, and documentation created for their platform unless a different model is contractually agreed. Third-party components, licensed vendor modules, open-source libraries, and any internal SoftDoes accelerators are documented with their respective licenses so there are no surprises. At project completion or at agreed milestones, we hand over repositories, CI/CD configurations, infrastructure-as-code scripts, and operational runbooks - everything your team needs to run, maintain, and extend the system independently.
Can you work with and extend our existing core banking system instead of replacing it?
Yes - SoftDoes often wraps and extends existing core systems via APIs, middleware, and new digital channels to avoid risky full core replacement. Examples include launching a modern mobile banking app, adding real-time fraud scoring, exposing open banking APIs, or building data analytics dashboards while keeping the current core in place. Banking software must integrate effectively with legacy systems, and during discovery we help evaluate when extension is sufficient versus when partial or full core modernization becomes the safer, more cost-effective long-term path. Custom software can modernize banking processes faster than rearchitecting legacy systems from scratch.
How does banking software development differ from general app projects?
Banking projects carry additional constraints: regulatory compliance, double-entry accounting, transaction integrity with idempotent processing, high availability, operational resilience, auditability, and strict change management across the software development lifecycle. Designs must satisfy regulators, auditors, risk committees, and security teams - not just end users - and mistakes in financial software can result in both financial and reputational damage. High transaction volumes require resilient banking infrastructure, and systems must handle high traffic spikes without latency issues. SoftDoes brings specific experience balancing usability, compliance, data security, and technical complexity in this demanding context.
What kind of support do we get after launch?
Options range from a focused hypercare period around go-live to ongoing support SLAs covering incidents, small enhancements, and monitoring of critical banking workflows. Incident handling prioritizes anything affecting customer access, transaction accuracy, or regulatory obligations, with clear escalation paths and defined response times. We monitor key metrics - transaction success rates, payment latency, failed jobs, reconciliation breaks - to catch issues before they affect customers or reporting. Automated monitoring is essential for detecting suspicious activity in financial transactions, and our support model ensures those alerts are acted on promptly.
How do you reduce risk on a complex banking initiative?
SoftDoes uses phased rollouts, proofs of concept for tricky integrations, and early involvement of risk, compliance, and information security teams - before code reaches production. We rely on sandbox environments with synthetic data, automated tests that verify both functionality and financial correctness, rehearsal of data migrations with balance reconciliation, feature flags, and detailed rollback plans. Critical error handling procedures must be in place to ensure financial integrity, and we communicate risks and trade-offs transparently throughout the project so leadership can make informed decisions at every stage.